
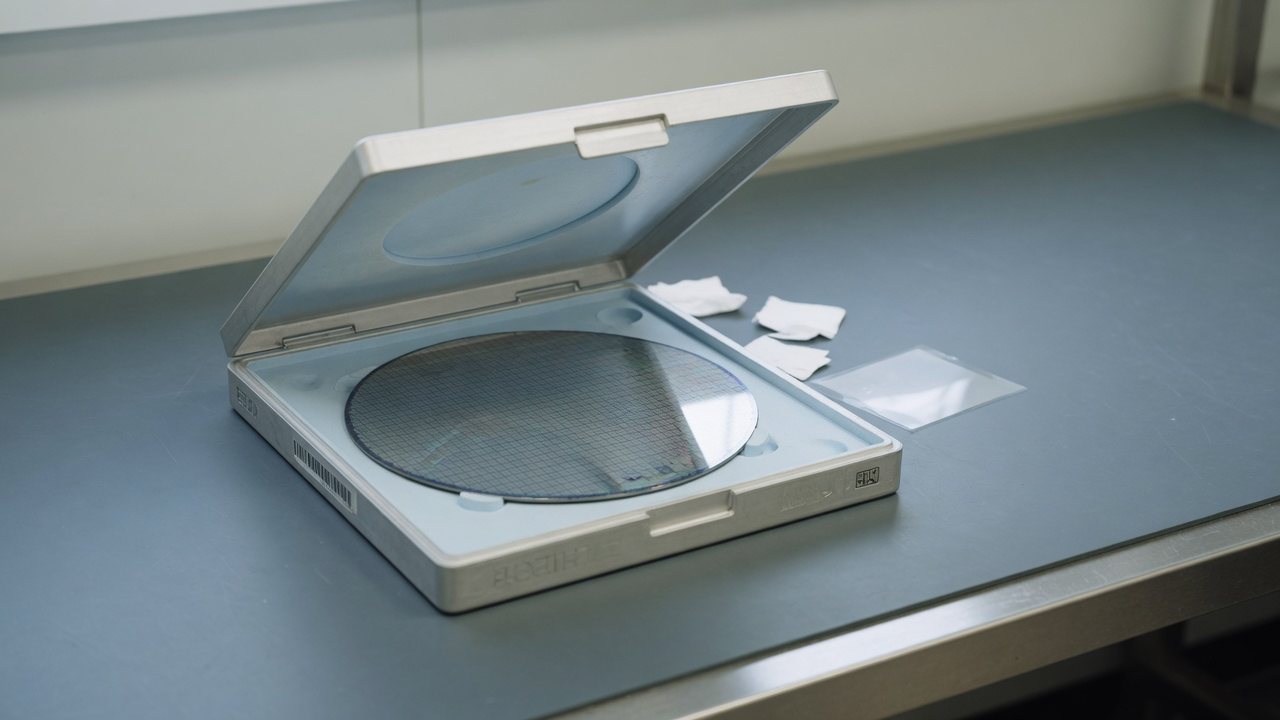
Lam Research Corporation reported fiscal first-quarter 2027 revenue of $8.22 billion on Wednesday, October 21, 2026, marking a 22% sequential increase and beating Wall Street expectations as artificial intelligence chip manufacturing drove aggressive wafer fabrication equipment demand. Operating margin climbed to 40.2% and non-GAAP diluted earnings per share reached $2.20, reinforcing semiconductor capital spending strength. Market data is as of 6:00 PM EDT on October 21, 2026, following the close of regular U.S. exchange trading.
The results underscore how the buildout of advanced AI accelerators and high-bandwidth memory (HBM) is directly benefiting critical semiconductor equipment makers. In its Form 8-K Exhibit 99.1 earnings release filed with the U.S. Securities and Exchange Commission, Chief Executive Officer Tim Archer highlighted that With AI driving higher semiconductor demand and greater device complexity, our focus on operational execution helped Lam deliver record revenue, profit, and earnings per share in the September quarter
. As chipmakers push the boundaries of 3D NAND vertical scaling, gate-all-around (GAA) nanosheets, and advanced packaging, wafer fabrication equipment (WFE) spending has accelerated across leading global foundries and memory suppliers.
Key Financial Takeaways from Q1 FY2027
- Accelerating Top-Line Growth: Total revenue reached $8.22 billion for the quarter ended September 27, 2026, surging 22% from $6.72 billion in the June 2026 quarter and expanding 54.4% compared to $5.32 billion in the prior-year period.
- Systems Revenue Inflection: Pure equipment shipments—classified as systems revenue—climbed 34.9% sequentially to $5.73 billion, reflecting aggressive customer installations of leading-edge etch and deposition tools.
- Robust Margin Expansion: Non-GAAP operating margin expanded 180 basis points sequentially to 40.2%, while non-GAAP gross margin rose to 52.4%, demonstrating strong operating leverage amid higher fab utilization.
- Cash Generation and Liquidity: Cash, cash equivalents, and restricted cash increased by $1.85 billion during the quarter to $7.45 billion, supported by robust operational cash flow.
- Confident Forward Guidance: For the second fiscal quarter ending December 27, 2026, Lam projected revenue of $8.60 billion (plus or minus $400 million) and non-GAAP diluted EPS of $2.33 (plus or minus $0.15).
Financial Performance Comparison
Lam Research demonstrated broad-based financial expansion across both U.S. GAAP and non-GAAP measures during the September 2026 quarter. For readers tracking broader industry trends, our guide to AI infrastructure stocks and semiconductor equipment demand provides deeper sector context on capital expenditure cycles.
| Metric (in thousands, except per-share data) | Q1 FY2027 (Sep 2026) | Q4 FY2026 (Jun 2026) | Q1 FY2026 (Sep 2025) | Q/Q Change |
|---|---|---|---|---|
| Systems Revenue | $5,732,907 | $4,249,848 | $3,547,565 | +34.9% |
| Customer Support & Other | $2,486,511 | $2,472,390 | $1,776,608 | +0.6% |
| Total Revenue | $8,219,418 | $6,722,238 | $5,324,173 | +22.3% |
| U.S. GAAP Gross Margin | 52.3% | 51.7% | 50.4% | +60 bps |
| Non-GAAP Gross Margin | 52.4% | 52.0% | 50.6% | +40 bps |
| U.S. GAAP Operating Margin | 40.0% | 37.4% | 34.4% | +260 bps |
| Non-GAAP Operating Margin | 40.2% | 38.4% | 34.8% | +180 bps |
| U.S. GAAP Diluted EPS | $2.19 | $1.81 | $1.04 | +21.0% |
| Non-GAAP Diluted EPS | $2.20 | $1.82 | $1.06 | +20.9% |
Systems Revenue vs. Customer Support Dynamics
The primary growth engine during the quarter was Lam Research’s systems business. Systems revenue surged 34.9% sequentially to $5.73 billion ($5,732,907 thousand), up from $4.25 billion in the previous quarter, while customer support-related revenue rose to $2.49 billion. According to the company’s filed disclosures, systems revenue includes sales of new leading-edge equipment in deposition, etch, clean, and other wafer fabrication processes.
As semiconductor architectures migrate to extreme aspect ratio etching for 300-layer 3D NAND and atomic layer deposition (ALD) for advanced logic nodes, Lam’s proprietary etch chemistry and chamber designs have seen intensified demand. Meanwhile, the recurring customer support-related business—which encompasses field maintenance, replacement parts, tool upgrades, and non-leading-edge equipment from the Reliant product family—maintained steady high-margin volume, generating $2.49 billion compared to $2.47 billion in the June quarter and $1.78 billion a year ago.
Geographic Distribution and International Demand
Geographic revenue mix revealed ongoing international divergence in wafer equipment procurement. Similar to trends previously analyzed in ASML’s lithography equipment shipments, customer demand in Asia continues to account for the overwhelming majority of global fab investment.
| Region / Geographic Market | Share of Q1 FY2027 Revenue |
|---|---|
| China | 35% |
| Korea | 20% |
| Taiwan | 18% |
| Japan | 9% |
| United States | 8% |
| Southeast Asia | 6% |
| Europe | 4% |
China represented 35% of Lam Research’s geographic revenue in the September 2026 quarter, followed by Korea at 20%, Taiwan at 18%, Japan at 9%, and the United States at 8%. The high concentration in China reflects domestic fab capacity expansion in mature and specialty trailing-edge nodes, where customers continue building local supply chains within prevailing trade compliance standards. Concurrently, strong shipments to Korea (20%) and Taiwan (18%) were driven by leading-edge memory producers and dedicated foundries scaling advanced packaging and high-bandwidth memory production lines.
Balance Sheet, Cash Flow, and Working Capital
Lam Research exited the quarter with substantial balance sheet flexibility. Lam Research’s cash, cash equivalents, and restricted cash balances grew to $7.45 billion at the end of the September 2026 quarter, up from $5.60 billion as of June 28, 2026. Management attributed this $1.85 billion cash accumulation primarily to operating cash flow generation, partially offset by ongoing capital expenditure commitments and share repurchases.
Deferred revenue climbed to $2.66 billion from $2.43 billion at the end of June. The company noted that its reported deferred revenue excludes tool shipments to customers in Japan, where revenue recognition is deferred until final on-site customer acceptance under U.S. GAAP. These Japanese shipments are carried in inventory at cost; the estimated future revenue from these pending shipments stood at $468.3 million as of September 27, 2026, compared to $490.2 million at the end of the June quarter.
Q2 FY2027 Outlook: Guidance Targets Record Pace
Looking ahead, management provided an upbeat financial target for the second fiscal quarter ending December 27, 2026. For the second fiscal quarter ending December 27, 2026, Lam Research projected revenue of $8.60 billion plus or minus $400 million, gross margin of 52.5% plus or minus 1%, and non-GAAP diluted EPS of $2.33 plus or minus $0.15.
Operating margin for the December quarter is guided to 40.5% (plus or minus 1%), with projected diluted share count estimated at 1.253 billion shares. Non-GAAP reconciling items between GAAP and non-GAAP results are projected to total approximately $3.3 million, consisting of intangible asset amortization and debt discount amortization.
Catalysts and Risks to Watch Next
For investors navigating equity markets and capital spending cycles (see our investor education hub for broader portfolio frameworks), key developments to monitor include:
- Wafer Fabrication Equipment (WFE) Capex Trajectory: Whether leading semiconductor manufacturers expand greenfield fab construction timelines in 2027 or pause after the initial wave of AI data center buildouts.
- High-Bandwidth Memory (HBM4) Transitions: Customer qualification schedules for next-generation 16-high HBM4 stacks, which require precision etch and deposition tools with tight tolerances.
- Geopolitical and Trade Policy Scrutiny: Any adjustments to bilateral export controls or tariff structures affecting the 35% revenue share generated from Mainland Chinese customers.
Sources & Further Reading
- Lam Research Corporation Form 8-K Exhibit 99.1 (Quarter Ended September 27, 2026) — U.S. Securities and Exchange Commission (EDGAR).
- Lam Research Corporation Form 8-K Current Report (October 21, 2026) — U.S. Securities and Exchange Commission (EDGAR).
- Lam Research Investor Relations — Quarterly Financial Tables and Earnings Presentation.
Disclosure: This article is for informational purposes only and is not investment advice.