
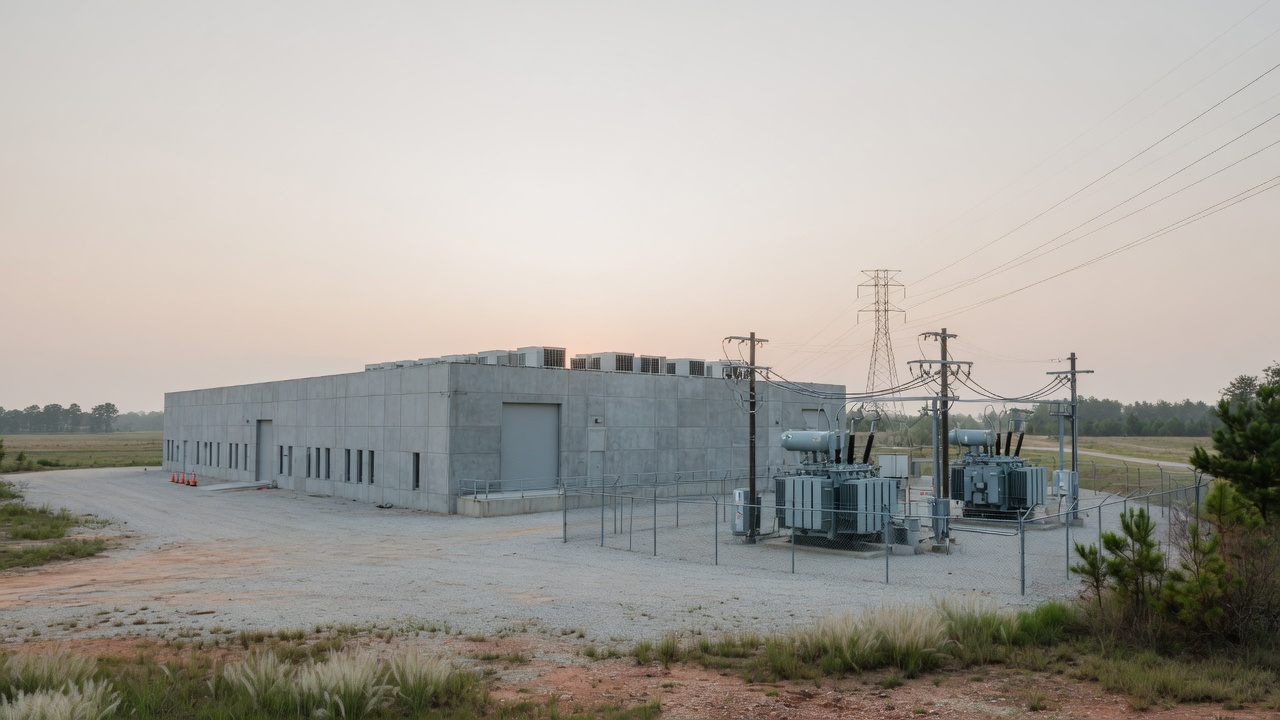
On September 25, 2026, CSDC Finance I, LLC, a wholly owned indirect subsidiary of CleanSpark, Inc. (NASDAQ: CLSK), closed its private placement of $2,276.0 million in 7.875% senior secured notes due 2031. The project debt underwrites the buildout of the 175-megawatt (MW) Sandersville Facility in Georgia, fully pre-leased to Meta Platforms under a 20-year triple-net contract generating approximately $6.6 billion in contracted cash flows. The closing concludes a capital raise commenced on September 17 and priced on September 18, 2026.
Key Takeaways
- Closed Project Financing: CSDC Finance completed the sale of $2,276.0 million in senior secured notes at an issue price of 98.500% of par, generating an illustrative pre-fee issue-price total of $2,241.86 million before underwriting discounts and transaction fees.
- Meta Credit Underpinning: The underlying asset—a 175 MW critical IT compute campus—is leased to Meta subsidiary Anviran, LLC, with Meta Platforms guaranteeing rent and operating expenses across a 20-year base term representing approximately $330.0 million in average annual net operating income (NOI).
- Structured Amortization & Parent Guarantee: Notes bear a 7.875% coupon payable semiannually on April 1 and October 1, amortizing post-construction to maintain a target debt service coverage ratio (DSCR), backed by CleanSpark’s parent completion guarantee.
Indenture Terms and Capital Structure Mechanics
The notes were issued under an indenture dated September 25, 2026, among CSDC Finance I, LLC as issuer, CSRE Properties Sandersville, LLC as subsidiary guarantor, CSDC Holdings I, LLC as parent pledgor, and U.S. Bank Trust Company, National Association as trustee and collateral agent. Morgan Stanley & Co. LLC served as representative of the initial purchasers.
The transaction establishes a dedicated project-financing vehicle for CleanSpark’s flagship hyperscale conversion. Disclosed proceeds are formally earmarked for three specific uses: financing the remaining development cost of the Sandersville campus, reimbursing CleanSpark for certain prior equity contributions, and funding debt service reserve accounts. The 98.500% original issue discount equates to an illustrative pre-fee issue value of $2,241.86 million, though reported net cash proceeds will reflect underwriting commissions and offering expenses.
| Financing Parameter | Indenture Terms | Disclosed Value |
|---|---|---|
| Aggregate Principal Amount | Rule 144A / Regulation S Senior Secured Notes | $2,276.0 million |
| Issue Price | 98.500% of par (original issue discount) | $2,241.86 million (illustrative) |
| Coupon & Payment Frequency | 7.875% fixed per annum; semiannual arrears | April 1 / October 1 |
| First Interest Payment | Semiannual accrued interest commences | April 1, 2027 |
| Maturity Date | Stated maturity unless redeemed earlier | October 1, 2031 |
| Call Protection | Non-call through Oct 1, 2028 (make-whole); then par call schedule | Up to 40% equity clawback |
| Amortization Structure | Semiannual post-construction targeting project DSCR | Commences post-delivery |
Interest payments are scheduled semiannually on April 1 and October 1, starting April 1, 2027. Unlike corporate revolving credit lines or corporate debentures, principal amortization begins after project delivery, structured to maintain a Target Project Debt Service Coverage Ratio (with an illustrative benchmark of 1.275x modeled in project filings). CSDC Finance holds the option to redeem the notes on or after October 1, 2028 at established redemption prices, while pre-2028 redemptions require customary make-whole premiums, accompanied by a standard 40% equity clawback allowance.
Meta Lease and Revenue Backlog
Credit support for the borrowing is anchored in a long-term agreement with Meta Platforms, Inc. According to CleanSpark’s Sandersville investor presentation filed on September 17, 2026, “Sandersville provides 175 MW of long-duration critical IT capacity to support Meta’s growing AI, data-processing and communications requirements.”
The tenant of record is Anviran, LLC, a wholly owned operating subsidiary of Meta Platforms, with Meta acting as parent guarantor for rental payments and operational expenses. The agreement spans a 20-year initial lease term, supported by two five-year extension options and a single 12-month extension option. The contract is structured as a 100% triple-net lease with a 3.0% annual rent escalator, insulating the operating entity from maintenance and utility fluctuations. Base-term contracted revenue totals approximately $6.6 billion, yielding projected net operating income averaging approximately $330.0 million annually across the initial 20-year commitment.
Phased project delivery targets initial rent commencement in the fourth quarter of 2027 following the handover of the first network hall on November 30, 2027. Full construction completion is slated for March 2028, aligning with the beginning of mandatory debt amortization.
Parent Balance Sheet and Risk Allocation
CleanSpark states that it controls a portfolio of more than 1.8 GW of power, land, and data centers across the United States. The closing of this project financing represents a distinct structural separation between project-level infrastructure debt and parent balance-sheet liabilities, similar to recent power acquisitions tracked across the sector, such as MARA Holdings restructuring its Texas power contracts.
However, CleanSpark remains financially linked through a customary parent completion guarantee. Under the guarantee, CleanSpark is obligated to fund CSDC Finance if bond proceeds, reserve funds, and prior equity contributions prove insufficient to achieve project completion. CleanSpark entered this transaction backed by substantial liquid reserves. As disclosed in its Form 10-Q for the quarter ended June 30, 2026, CleanSpark held:
- Cash and Cash Equivalents: $202.6 million in unrestricted cash (plus $3.7 million in restricted cash).
- Digital Asset Holdings: Total bitcoin holdings valued at $714.3 million ($592.1 million current and $122.2 million noncurrent).
- Total Assets & Leverage: Total balance-sheet assets of $2,702.2 million against long-term debt of $1,780.0 million and total liabilities of $1,940.9 million.
CleanSpark’s capital structure also connects to broader tech funding initiatives, as seen in Meta’s aggressive infrastructure expansion and recent corporate bond issuances like DICK’S Sporting Goods raising $1.0 billion in long-term debt.
Risks and What to Watch Next
While the 20-year triple-net lease with Meta provides a high-investment-grade tenant profile, project execution carries distinct risks. Construction delays, supply-chain interruptions for high-voltage electrical switchgear, or cost inflation could trigger CleanSpark’s obligations under the parent completion guarantee before rental cash flows commence in late 2027.
Investors should track two pivotal milestones: CleanSpark’s upcoming fiscal year-end Form 10-K filing detailing final net proceeds and transaction costs, and construction progress toward the November 30, 2027 initial network hall delivery date in Sandersville.
Sources
- SEC Form 8-K: CleanSpark, Inc. Closing of Senior Secured Notes (September 25, 2026)
- SEC Form 8-K Exhibit 99.1: Sandersville Investor Presentation (September 17, 2026)
- SEC Form 10-Q: CleanSpark, Inc. Quarterly Report for the Period Ended June 30, 2026
Disclosure: This article is for informational purposes only and is not investment advice.